All Categories
Featured
Finding Best Medicare Supplement Policies for 2026
Table of Contents
Instead you respond to a set of health questions, and the carrier checks prescription records. That opens the door to people who would battle with a fully underwritten policy applicants in their seventies, individuals managing diabetes or heart disease, individuals who have had cancer. It is often the only life cover readily available to them, and it is truly helpful for that factor.
Final expenditure insurance costs more per thousand dollars of cover than a fully underwritten policy would for a healthy candidate. If you remain in health and desire a bigger benefit, ask us to estimate a standard policy along with it before you decide. This is the single most important thing to comprehend, and the thing frequently glossed over.
Insurance in Camarillo CAThis is what you want, and most fairly healthy candidates qualify for it. The policy pays a minimized percentage of the advantage if death happens in the very first two or 3 years, increasing to the full quantity afterwards. No health concerns at all, however if death occurs within the first two years the policy usually returns only the premiums paid plus interest not the death advantage.
Insurance in Camarillo CAMarketing for last expense insurance hardly ever distinguishes between these. Term and whole life over one lifetimeIt matches individuals whose remaining insurance coverage need is small and particular.
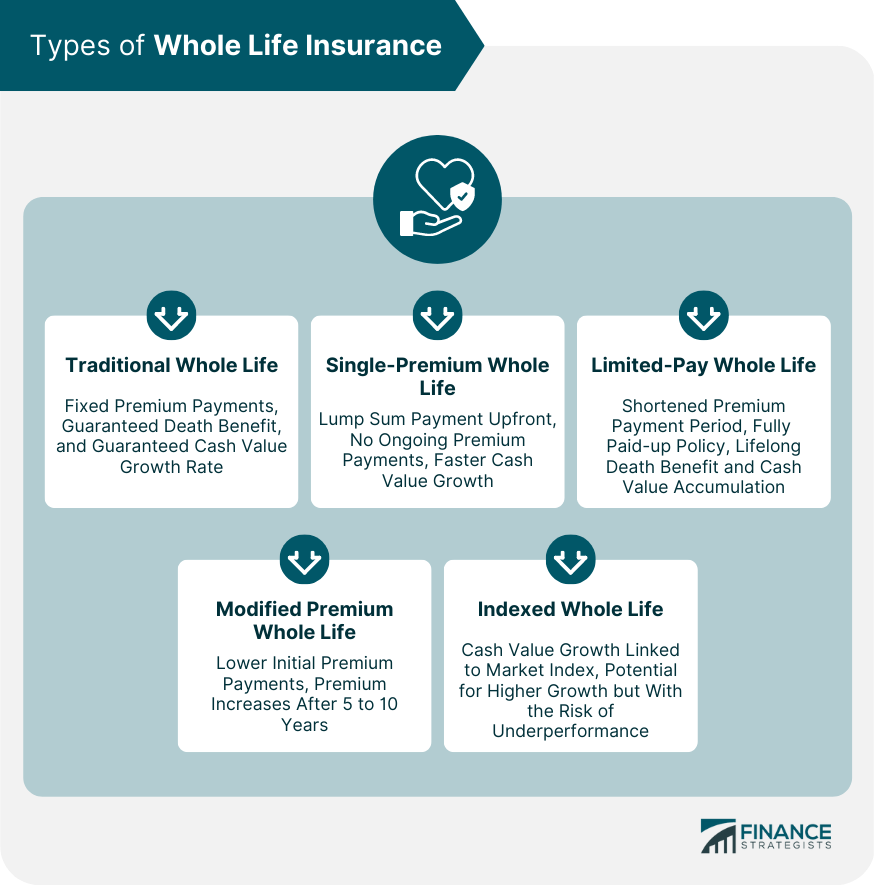
How Universal Life Insurance Functions for Family Security
It matches individuals who can not pass full underwriting however can answer a short health questionnaire honestly and receive a level benefit. And it matches individuals who desire the certainty of long-term cover at a premium that fits a fixed retirement income. It does not suit somebody still changing an income.
A final cost insurance policy pays cash to the recipient you call. Call a person who will in fact be present and organized in the days after your death, and inform them the policy exists.
Some people prefer to appoint a part of the benefit directly to a funeral provider so the arrangements are paid without the household fronting money. That is a separate plan from a pre-need or pre-paid funeral contract, which is regulated in a different way and is not insurance coverage in the same sense. If you already hold one, tell us before purchasing, so you do not pay two times for the exact same thing.
Verify which you have. Rates for the same health profile differ materially between carriers, and the difference is not visible from one quote. Work out the actual expected expense in your area, add a margin, and buy that. Paying premiums for decades on a benefit two times the size of the requirement is money leaving the household each month.
Navigating 2026 Medicare Advantage Enrollment
Speak to us before canceling; minimizing the face amount is often possible. Keep the policy number where the household will discover it. Do not rate the amount, and do decline a round number from an advertisement. Price the real need where you live, since funeral expenses differ extensively by area and by what you choose.
You are entitled to buy just the items you want rather than a bundle. Ring 2 or three service providers near you and request that list. Build up the items your household would reasonably select the service, the casket or cremation, the plot or urn, the transport, the death certificates.
And if you currently hold a pre-need or pre-paid funeral agreement, part of the expense may already be covered, in which case a smaller last expense insurance policy will do. Sizing it this way typically produces a lower number than the one people presume, which implies a lower premium every month for the rest of your life.
Or call. We will inform you which benefit type you receive before you apply, not after.
Burial insurance, also called funeral insurance, is a valuable tool for loved ones spending for a departed relative or friend's funeral, funeral, headstone, urn, and other last expenses. It is essentially a life insurance policy, but with a much smaller sized benefit amount than traditional life insurance. It's typically bought to cover final plans, but can also be utilized to pay the deceased's financial obligations, consisting of medical costs, credit card costs, mortgage loans, and personal loans.

Latest Posts
Comparing Term Life Rates
Medicare Part D Enrollment Guide for Seniors
Best Medicare Supplement Coverage Comparison Tips